Dan Stickel
124:26 - 125:23
“The material impact between S and S as amended from a modeling standpoint is the inclusion of the pass-through entity tax.”
- Speaker
- Dan Stickel
- Timestamp
- 124:26 – 125:23
- Transcript
- Alaska Legislature: MSC2-20260626-1410
- Community
- Alaska News
- Location
- Alaska
From the transcript
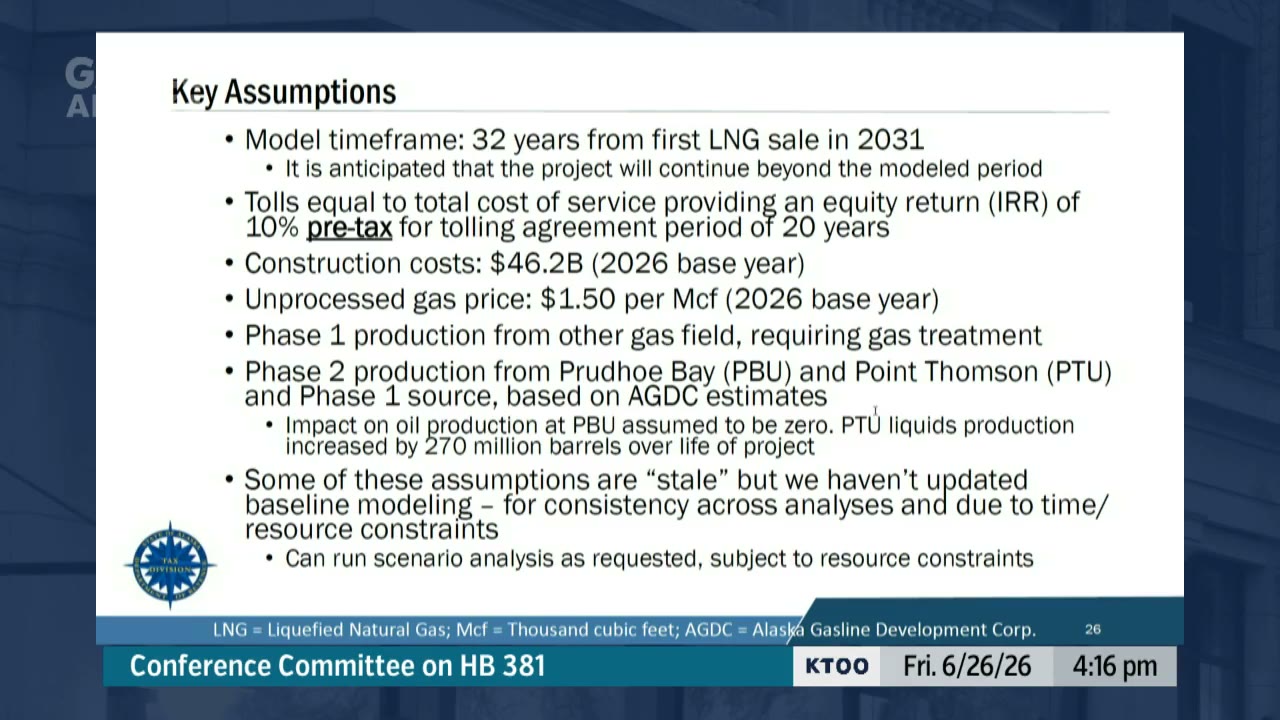
But that said, these are the assumptions that underlie the analysis that we are about to walk through. We do have some sensitivity analysis built into the presentation, and we are happy to run additional scenarios for the committee as we have for multiple committees going throughout this process. So slide 27, so for this slide— for this presentation we were asked to focus specifically on the Senate versions of the bill, specifically version S which came out of the Senate Finance Committee and then version S as amended which came off of the the floor. The material impact between S and S as amended from a modeling standpoint is the inclusion of the pass-through entity tax. In each of these scenarios, we show the impact if the full AKLNG project proceeds under each scenario.
Related Coverage
Alaska's gas-pipeline bill now carries a tax on Hilcorp and others
A permanent tax on pass-through oil companies like Hilcorp is riding inside Alaska's gas-pipeline bill — and it kicks in by 2028 whether the pipeline gets built or not.

State economist: even with tax breaks, the gas line barely works
Even with the Senate's tax breaks, Alaska's gas project still costs more to make than Asia pays for it — and one lawmaker put it bluntly: "It seems like they don't work."